Jefferson, Oldham, Bullitt & Hardin
Louisville Metro
Spring hail, Ohio Valley windstorms and older brick housing stock. The 2008 Ike windstorm showed how far inland a tropical remnant can reach.
Statewide · all 120 counties
Your insurer agreed the damage is covered — then sent a number that won’t pay for the repair. Kentucky Insurance Appraiser builds an independent, line-by-line valuation and carries it through the appraisal clause in your policy.
Call (844) 537-1427See our services
Appraisal settles how much, not whether. If the claim was denied, start with a Kentucky attorney.
Compare both estimates in the appraisal payoff estimator — fees included.
Map proof-of-loss, holdback and suit dates with the claim timeline builder.
Why owners call us
Most underpaid Kentucky claims aren’t denied. They’re just short — a roof slope left off, a steep charge missing, siding that can’t be matched, a code item nobody priced. Kentucky Insurance Appraiser exists for the space between “covered” and “paid in full.”
We inspect and measure the property ourselves, price the repair for the county it sits in, and put every difference with the carrier’s estimate in plain English. When appraisal isn’t the right tool, we say so on the first call.
Kentucky Insurance Appraiser at a glance
Services
Eleven services built around one job: a valuation of your loss that holds up. Start with an estimate review, or bring us in after appraisal has been demanded.
 01Appraisal Clause RepresentationWe serve as your named appraiser once the appraisal clause is invoked on a Kentucky property claim.
 02Homeowners Insurance AppraisalAppraisal help for Kentucky houses, condos under HO-6 policies and rental homes when the claim number falls short.
 03Commercial & HOA AppraisalAppraisal for Kentucky retail, office, warehouse, church, apartment and condo association property claims.
 04Roof & Hail Damage AppraisalIndependent appraisal for Kentucky roof and hail claims where repair scope or pricing is in dispute.
 05Tornado & Wind Damage AppraisalAppraisal for Kentucky tornado, straight-line wind and windstorm claims when the payout doesn’t match the damage.
 06Water Damage AppraisalAppraisal for burst pipe, appliance leak and sudden discharge claims in Kentucky homes and buildings.
 07Fire & Smoke Damage AppraisalAppraisal for Kentucky fire, lightning, smoke, soot and contents claims when the settlement falls short.
 08Ice Storm & Freeze Damage AppraisalAppraisal for Kentucky ice storm, ice dam, falling tree and frozen pipe claims when the payout is too low.
 09Farm, Barn & Equine Property AppraisalAppraisal for Kentucky horse barns, tobacco and hay barns, pole barns, fencing and farm outbuilding claims.
 10Insurance Estimate ReviewA line-by-line review of your carrier’s Xactimate estimate, before or instead of formal appraisal.
 11Umpire ServicesNeutral umpire services for Kentucky appraisals when the two party appraisers can’t reach agreement.
Quick check
Enter the two numbers you already have. A wide gap is worth a conversation with a Kentucky Insurance Appraiser. A narrow one may close faster with a documented supplement.
The full appraisal payoff estimator adds appraiser and umpire fees and shows the break-even point.
Amount in dispute—
Figures are illustrative. Results update as you type.
The process
The appraisal clause turns an open-ended argument into a defined process with a binding result. Here is how Kentucky Insurance Appraiser moves a file from first call to award.
Check that you and the insurer agree a covered loss happened and disagree mainly about how much it costs to repair or replace.
Invoke the appraisal clause in writing, following the notice requirements in your policy.
Each side selects a competent, impartial appraiser within the window most policies set after the demand.
The two appraisers agree on a neutral umpire, or a court of record where the property sits can appoint one.
The appraisers inspect the property, review the documents and each prepare a line-item estimate of the loss.
The appraisers work through the line items together and send only the items they cannot resolve to the umpire.
A written award signed by any two of the three sets the amount of loss, and the insurer pays under the policy terms.
Six claim climates
Tornado alley in the west, karst in the south, ice in the Bluegrass, flash floods in the mountains. Each region writes a different kind of estimate.
Spring hail, Ohio Valley windstorms and older brick housing stock. The 2008 Ike windstorm showed how far inland a tropical remnant can reach.
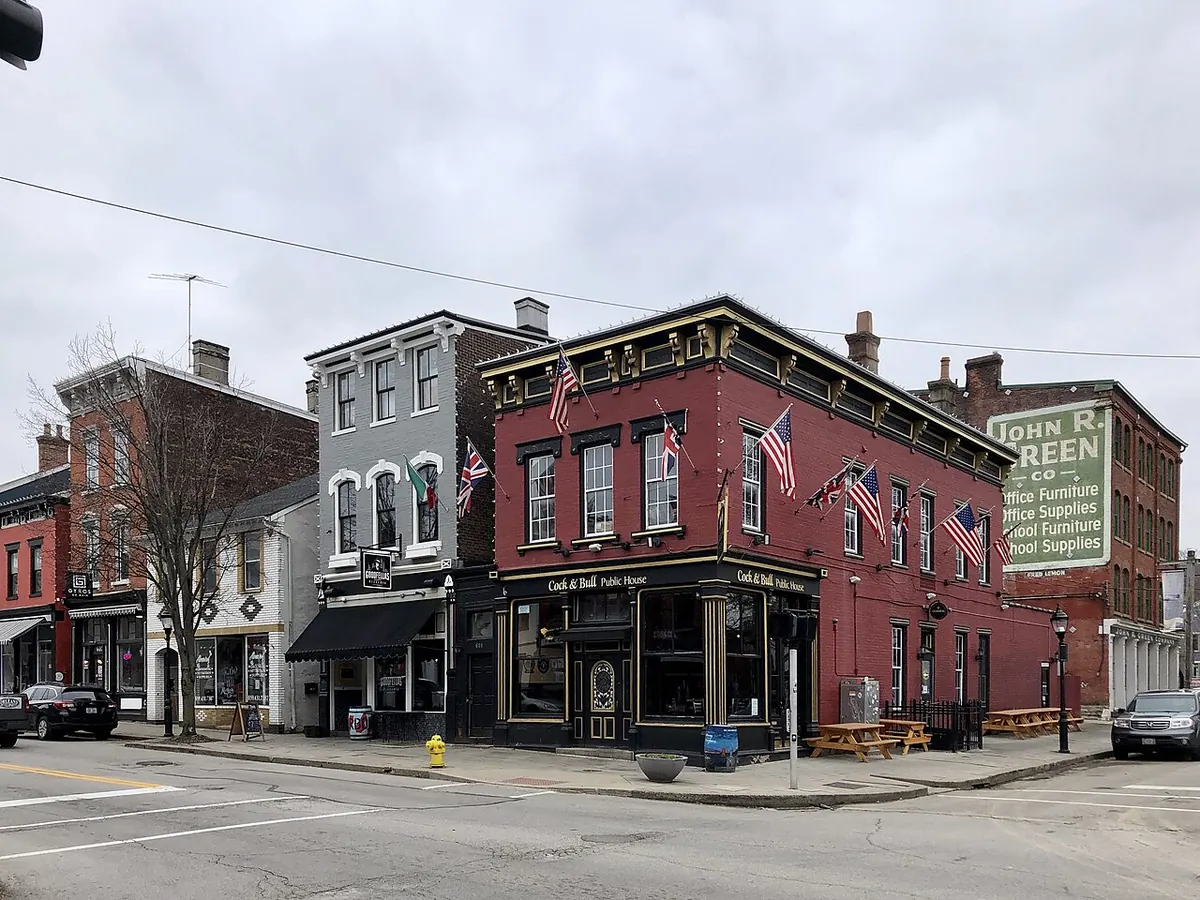
Nineteenth-century row houses, river-town flooding risk and hillsides prone to slippage — plus the same hail tracks that cross the Cincinnati metro.
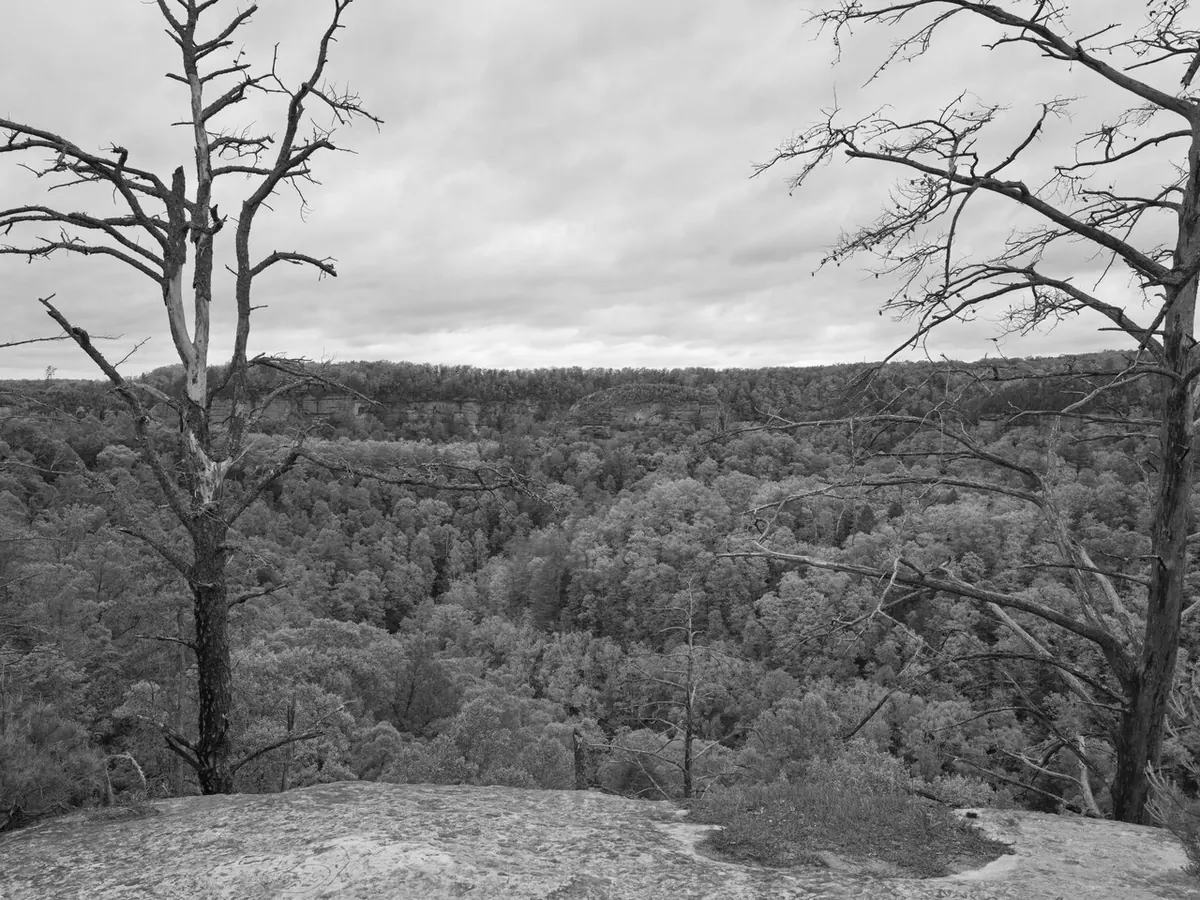
Tornado country. The December 2021 outbreak and the 2009 ice storm both left their deepest marks west of I-65.
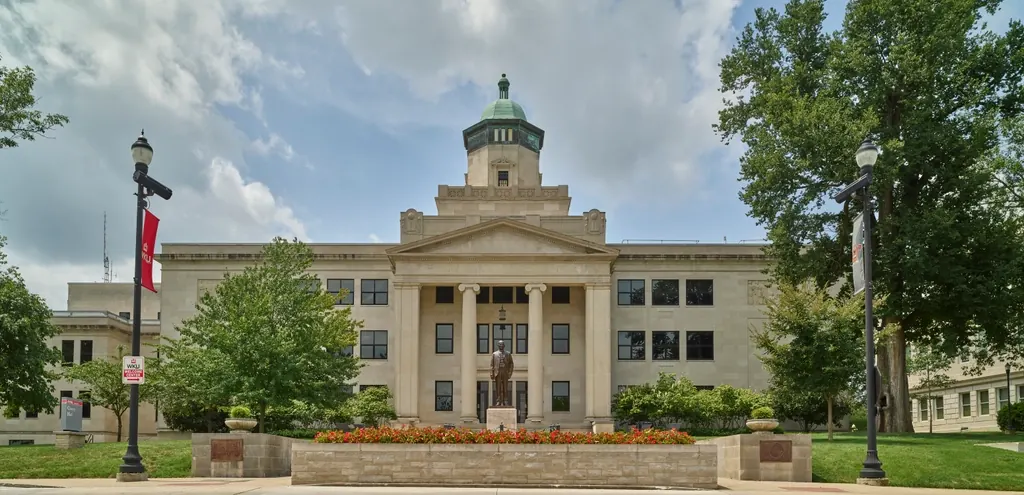
Karst ground, sinkholes and fast growth around Bowling Green, which took an overnight tornado hit in December 2021.
Storm memory
Every Kentucky Insurance Appraiser file is read against this history: what failed, what got missed, and what estimates tend to leave out after a big event.
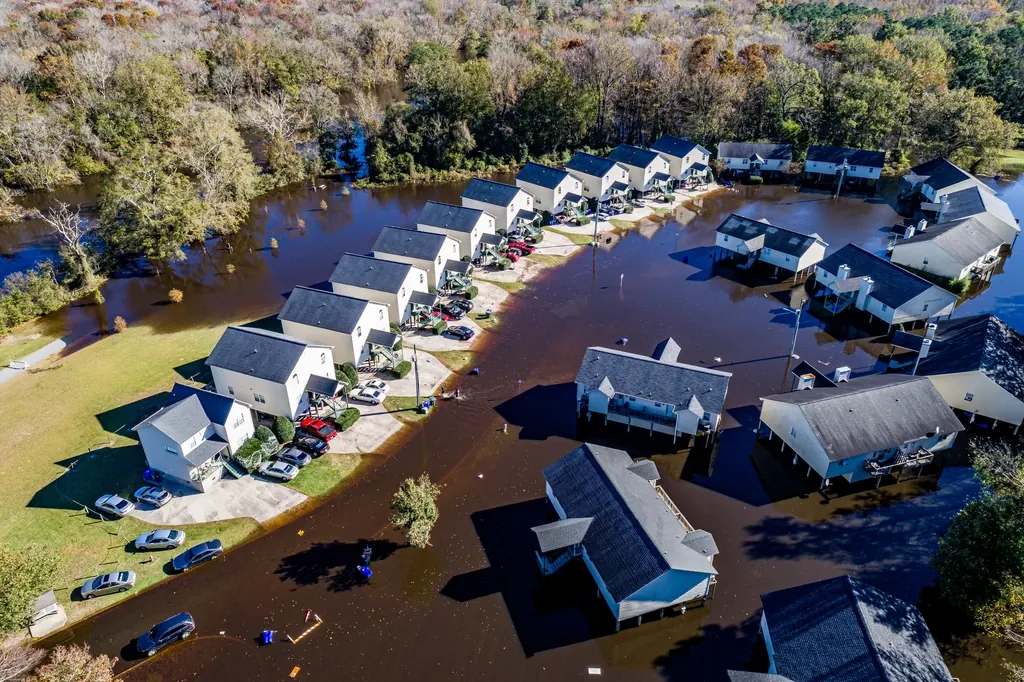
Record river levels flooded Louisville, Paducah and much of the Ohio Valley, and changed how river towns built.
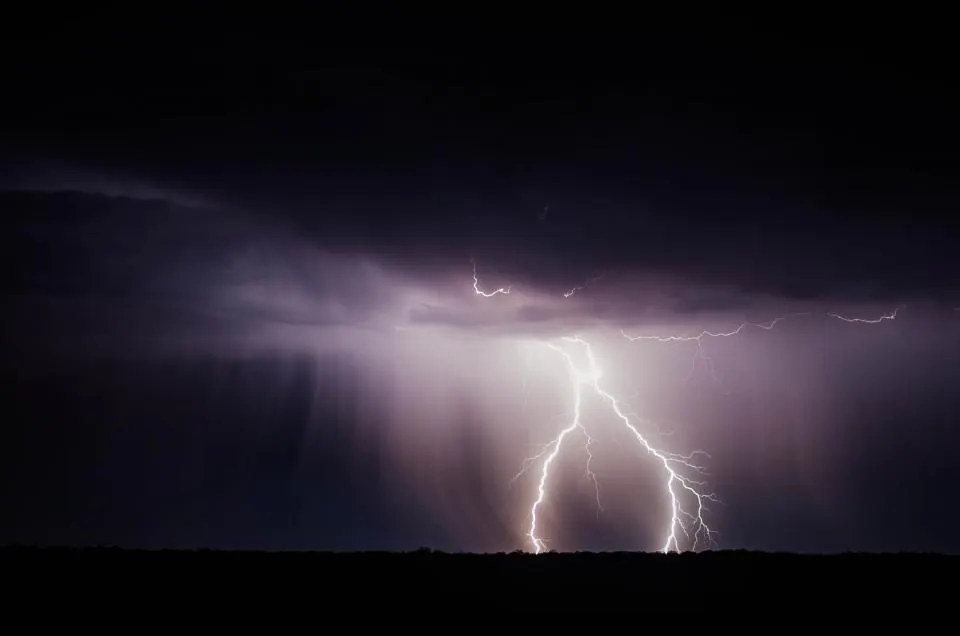
A wave of tornadoes crossed the state, including the Brandenburg and Louisville tornadoes.
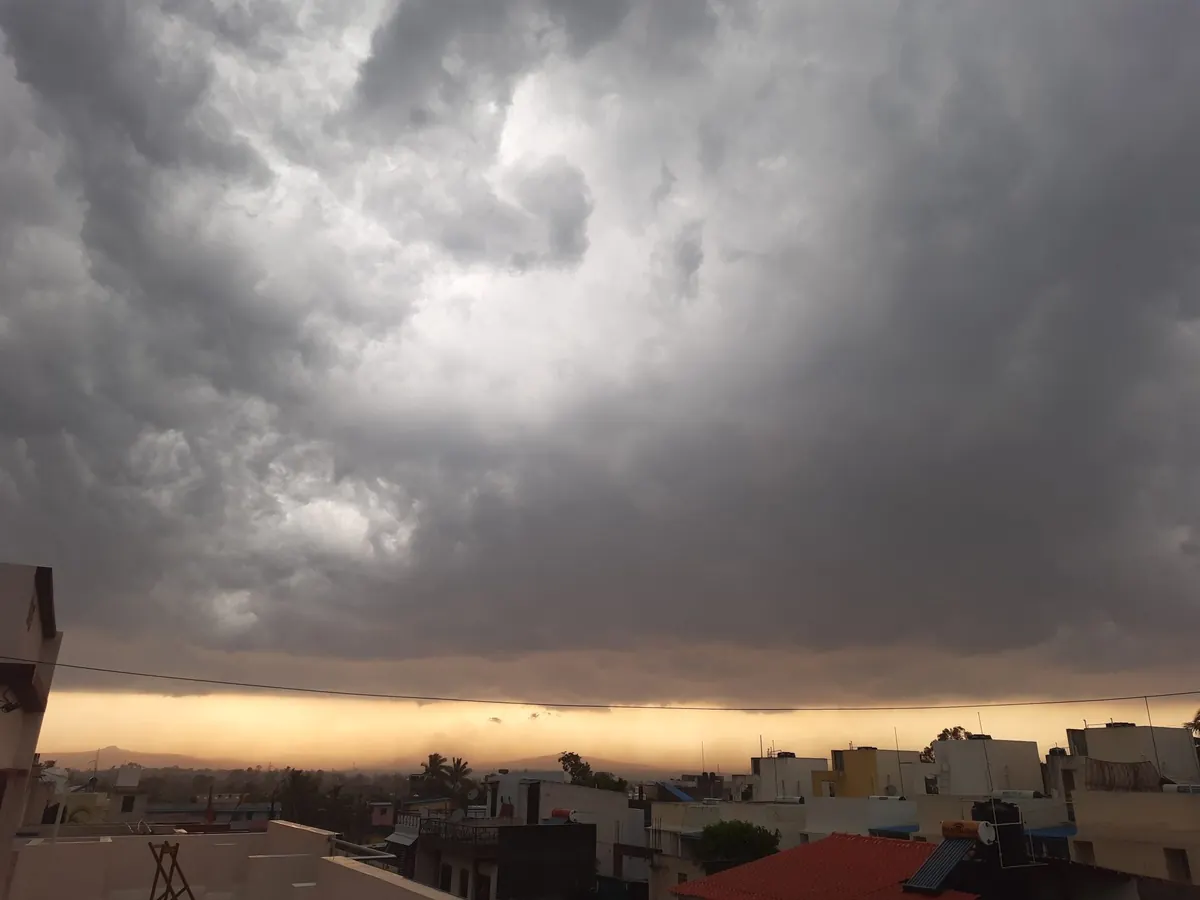
Hurricane Ike’s remnants brought hurricane-force gusts to the Louisville area and a long statewide cleanup.
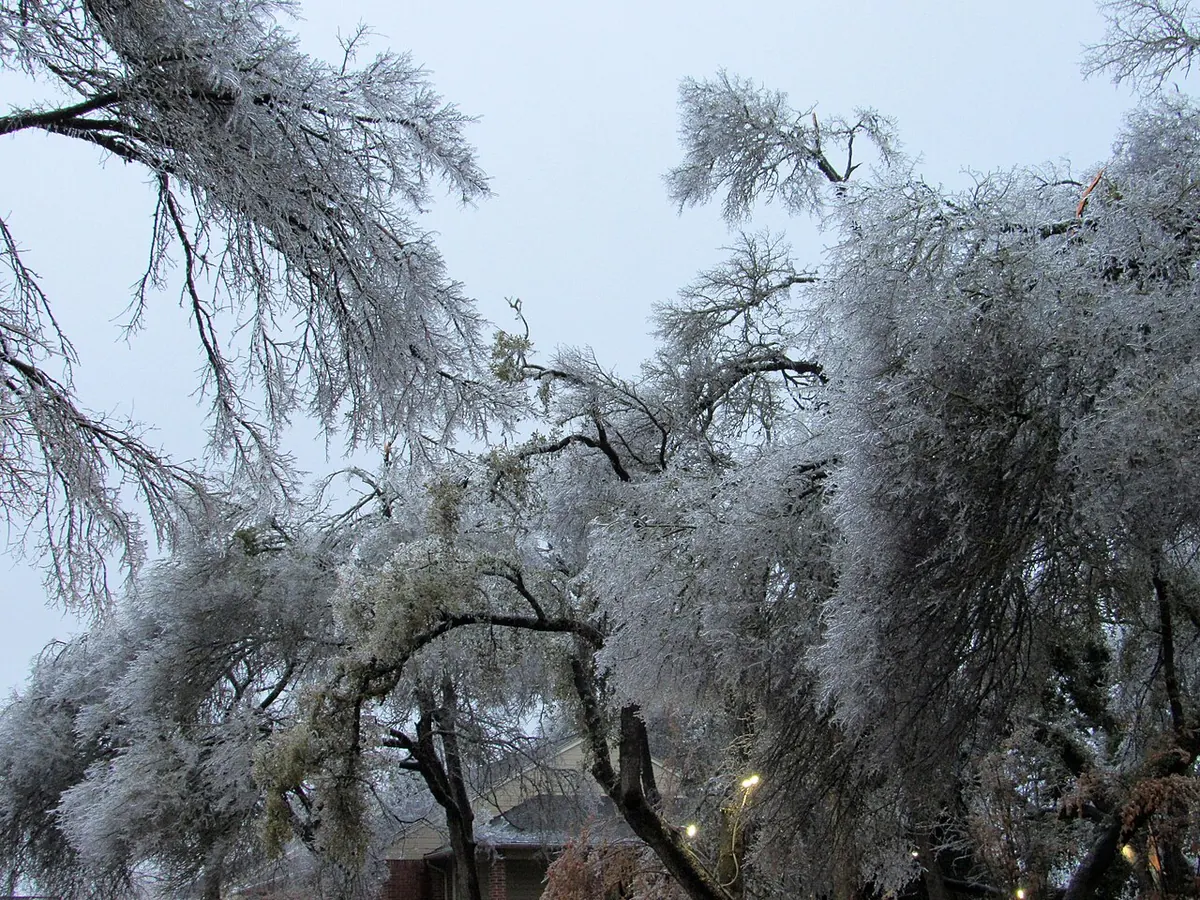
Heavy ice brought down trees and power lines across western Kentucky, Paducah included.
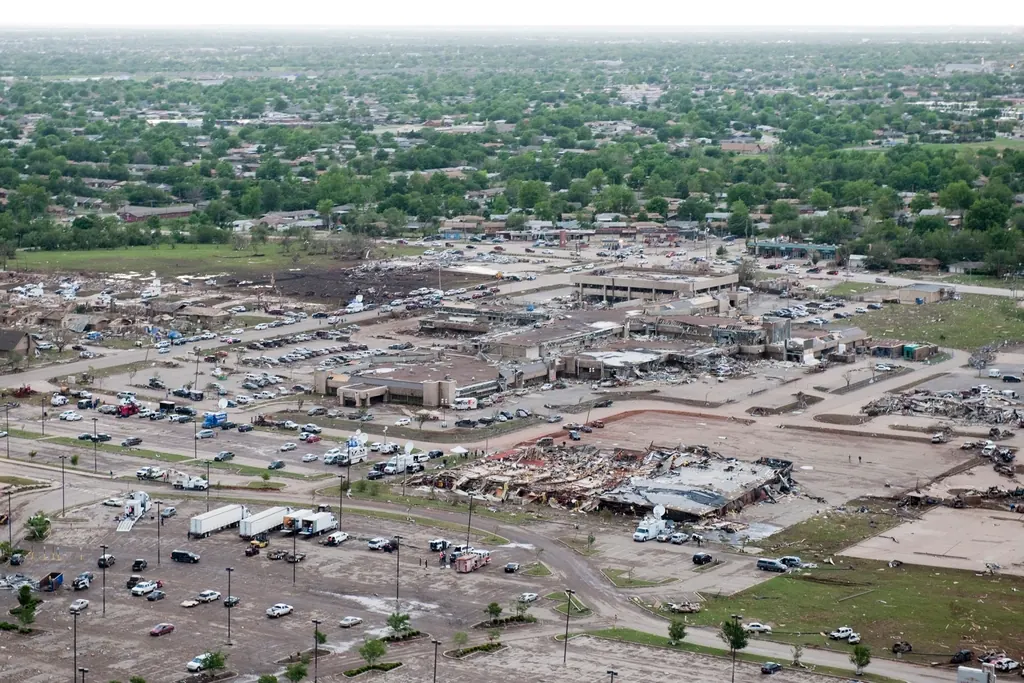
Overnight tornadoes struck Mayfield, Dawson Springs and Bowling Green in one of the state’s worst disasters.
Flash flooding in late July swept through hollows in Perry, Knott, Breathitt and Letcher counties.
Free & private
Run the numbers before you call. Every tool works in your browser — nothing you type is sent or stored.
 EstimatorAppraisal Payoff EstimatorCompare the carrier’s estimate to yours, weigh appraisal costs and see the net increase you might keep.
 CalculatorRCV & ACV Holdback CalculatorEstimate your first ACV check, the depreciation held back and what you can recover after repairs.
 CalculatorRoof Measurement CalculatorTurn a footprint and pitch into roofing squares, add waste and compare against the carrier’s count.CalculatorPercentage Deductible CalculatorSee what a 1%, 2% or 5% wind and hail deductible really costs next to a flat deductible.PlannerClaim Timeline BuilderBuild a dated list of claim milestones from your date of loss and export it to your calendar.CheckupAppraisal Readiness CheckupAnswer 10 yes-or-no questions to see if your claim file is ready for appraisal and what to fix first.CalculatorStorm Tree Removal Coverage CalculatorEstimate how much of a storm tree removal bill your homeowners policy may cover and what you might pay.
Straight talk
A few common beliefs that cost owners money — and what is usually true instead. Your policy language always controls.
Questions
Short answers about how appraisal works, what it costs and when it’s the wrong move.
We value property damage when you and your insurer agree the loss is covered but disagree on what it costs. As your appointed appraiser we inspect, build an independent line-item estimate, work with the carrier’s appraiser and, if needed, take unresolved items to a neutral umpire.
No. A public adjuster handles the whole claim for a fee. An appraiser works inside the policy’s appraisal clause on one question — the amount of loss. We don’t negotiate the rest of the claim and we don’t give legal advice.
When coverage has been accepted, you have the carrier’s itemized estimate, and the gap to your contractor’s number is meaningful — often more than about 10 percent or several thousand dollars.
No. Appraisal sets the amount of loss. Coverage disputes, denials and bad-faith questions belong with a Kentucky attorney, and the Kentucky Department of Insurance takes consumer complaints.
Each side usually pays its own appraiser and splits the umpire. Our fee is put in writing before work starts, and the first conversation is free.
Yes. We take appraisal and review work in all 120 Kentucky counties, from Paducah and Hopkinsville to Lexington, Covington, Pikeville and Ashland.
Guides
Practical articles from Kentucky Insurance Appraiser on policy wording, documentation and claim strategy.
A plain-English walk through the appraisal clause in most Kentucky property policies, from the written demand to the signed award, and the limits on what appraisal decides.
Kentucky’s ice storms and hard freezes create tree, roof and plumbing claims with their own policy conditions. Here is what to photograph, save and write down.
The weeks after a tornado decide how smoothly the claim goes. This checklist covers mitigation, living expenses, contents and contractor contracts.
Before you sign off
A short review by a Kentucky Insurance Appraiser can keep you from closing a claim that won’t cover the repair.
Where we work
Kentucky Insurance Appraiser takes work in every county. These are the communities where our files come from most often. Don’t see yours? Ask us — the answer is almost certainly yes.
